The smart Trick of Kam Financial & Realty, Inc. That Nobody is Talking About
Table of ContentsThe Ultimate Guide To Kam Financial & Realty, Inc.7 Easy Facts About Kam Financial & Realty, Inc. DescribedThe Only Guide for Kam Financial & Realty, Inc.The Basic Principles Of Kam Financial & Realty, Inc. Everything about Kam Financial & Realty, Inc.Not known Facts About Kam Financial & Realty, Inc.Kam Financial & Realty, Inc. Things To Know Before You Get ThisThe Facts About Kam Financial & Realty, Inc. Revealed
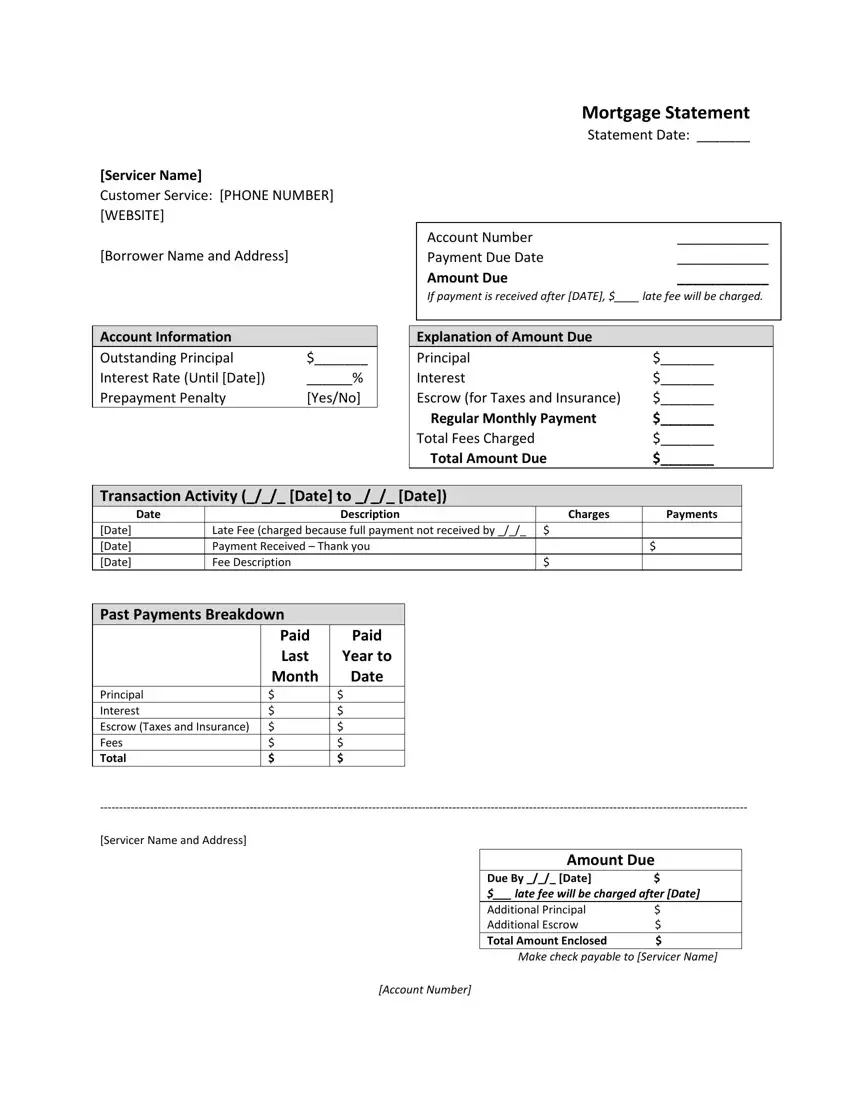
If your local region tax price is 1%, you'll be billed a building tax obligation of $1,400 per yearor a monthly residential property tax of $116. We're on the last leg of PITI: insurance. That's not always a poor thing.What a relief! Keep in mind that nice, expensive escrow account you had with your real estate tax? Well, think what? It's back. Similar to your real estate tax, you'll pay part of your house owner's insurance coverage costs on top of your principal and interest repayment. Your lender gathers those payments in an account, and at the end of the year, your insurance policy company will draw all that cash when your insurance coverage settlement is due.
Little Known Questions About Kam Financial & Realty, Inc..
It's indicated to secure the lending institution from youwell, at the very least from the possibility that you can't, or just flat do not, make your home loan repayments. Of training course, that would certainly never be youbut the lender does not care. If your down repayment is much less than 20% of the home's cost, you're going to get penalized PMI.
If you come from an area like among these, do not overlook your HOA cost. Relying on the age and size of your residence and the services, this might include anywhere from $50$350 to the amount you pay each month for your general real estate costs. There are numerous types of mortgages and they all bill different regular monthly settlement amounts.
Things about Kam Financial & Realty, Inc.
Because you wish to get a mortgage the clever means, get in touch with our pals at Churchill Mortgage - mortgage broker california. They'll walk with you every action of the way to place you on the ideal course to homeownership
The smart Trick of Kam Financial & Realty, Inc. That Nobody is Discussing
This is one of the most usual sort of home mortgage. You can select a term up to thirty years with the majority of lending institutions. A lot visit homepage of the early payments pay off the rate of interest, while a lot of the later settlements settle the principal (the first quantity you borrowed). You can take a table car loan with a set interest rate or a floating rate. https://www.pageorama.com/?p=kamfnnclr1ty.
The majority of loan providers bill around $200 to $400. This is typically negotiable. mortgage lenders in california.: Table car loans give the discipline of routine settlements and a set date when they will certainly be repaid. They provide the assurance of knowing what your settlements will certainly be, unless you have a drifting price, in which instance repayment amounts can change
What Does Kam Financial & Realty, Inc. Do?
Rotating credit history financings function like a giant overdraft. Your pay goes straight into the account and bills are paid out of the account when they're due. By maintaining the funding as low as possible at any moment, you pay less rate of interest because lending institutions determine rate of interest daily. You can make lump-sum payments and redraw cash as much as your limitation.
Application costs on revolving credit score home car loans can be up to $500. There can be a charge for the day-to-day financial deals you do with the account.: If you're well ordered, you can settle your home mortgage faster. This additionally fits people with unequal income as there are no set repayments.
The Ultimate Guide To Kam Financial & Realty, Inc.
Subtract the savings from the overall car loan amount, and you just pay interest on what's left. The even more cash you keep throughout your accounts daily, the extra you'll save, due to the fact that interest is determined daily. Connecting as many accounts as possible whether from a partner, moms and dads, or other relative indicates even less rate of interest to pay.

Not known Factual Statements About Kam Financial & Realty, Inc.
Repayments begin high, however reduce (in a straight line) with time. Charges are similar to table loans.: We pay less interest overall than with a table lending due to the fact that very early repayments consist of a higher settlement of principal. These might fit consumers that anticipate their income to go down, as an example, if one partner strategies to provide up work in a few years' time.
We pay the interest-only component of our repayments, not the principal, so the repayments are lower. Some debtors take an interest-only finance for a year or 2 and afterwards switch to a table financing. The normal table finance application fees apply.: We have extra cash for various other points, such as remodellings.
Unknown Facts About Kam Financial & Realty, Inc.
We will certainly still owe the sum total that we borrowed up until the interest-only period ends and we start paying back the car loan.
The home loan note is normally taped in the general public documents along with the mortgage or the deed of count on and works as proof of the lien on the residential property. The home loan note and the home mortgage or act of count on are two different documents, and they both offer various legal purposes.